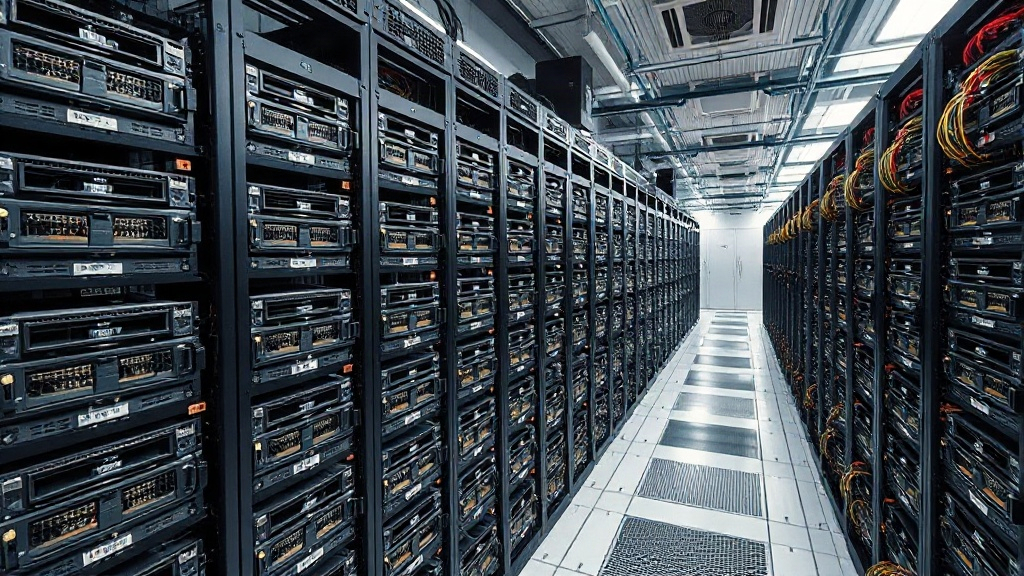
Iluvatar CoreX unveiled the Tiangai 300 IXL144 last week—a 144-GPU supernode breaking the record for single-cabinet density. But what matters for European SMBs isn’t the specs: Chinese AI GPU infrastructure alternatives are maturing fast, and understanding this shift is critical for vendor resilience and negotiating power.
Iluvatar CoreX unveiled the Tiangai 300 IXL144 last week—a 144-GPU supernode breaking the record for single-cabinet density in AI infrastructure. But where this matters for European SMBs isn’t the specs sheet. It’s what this signals about vendor resilience and NVIDIA’s shrinking margin of control.
The density benchmark, and what it really means
The announcement came October 13 at Shanghai’s China International Industry Fair. The cabinet squeezes 144 GPUs, 18 CPUs, and approximately 10.1 terabytes of memory into one physical rack. According to Iluvatar, the cost per million valid inference tokens runs 40% lower than “mainstream international alternatives”—which is market-speak for NVIDIA.
Notably, the Tiangai chip series has already powered deployments at the 10,000-card scale. This isn’t vaporware. And it’s not surprising. Seven Chinese AI vendors unveiled full-system architectures at the World AI Conference in Shanghai earlier this year. NVIDIA’s market share in Chinese AI chips fell to 34% in H1 2026. The bifurcation is real and accelerating.
But here’s the thing—this isn’t new news for China watchers. MetaX and Enflame both launched supernodes months before Iluvatar. What is notable is the density benchmark and the speed of the buildup. The timeline compressed. Suddenly, there’s a crowded field of domestic alternatives, each closing the performance gap and underpricing NVIDIA.
The vendor lock-in angle
If you run a logistics firm, a distributor, or a manufacturing operation with 50 to 200 people and you’ve embedded your AI workloads on NVIDIA’s CUDA ecosystem, congratulations—you’ve created productivity wins. You’ve also locked yourself in. The cost to migrate models and application logic to a competing vendor’s GPU APIs and frameworks represents 20-30% of the original development spend. Switching is possible, but it’s expensive enough that NVIDIA knows you’re sticky.
NVIDIA knows everyone is sticky. That’s where their pricing power comes from. They can take margin because you can’t leave cheaply.
Now imagine the negotiating table shifts. NVIDIA’s dominance was global. If Chinese clusters can deliver 40% cost savings at comparable performance, suddenly NVIDIA stops being the default vendor and becomes a vendor—and one that can’t ignore margin pressure. When hyperscalers and regional cloud providers (the ones ordering thousands of GPUs annually) use Chinese alternatives as negotiating leverage, that pressure eventually reaches smaller buyers. Your contract terms and your per-token pricing get better.
What European SMBs should do now
First: audit your current GPU infrastructure spend and map out your CUDA dependency. How deeply are your workloads locked into NVIDIA-specific APIs like cuBLAS, cuDNN, or Thrust? Could you port portions of your pipeline to open standards like vLLM or ONNX?
Second: start evaluating multi-vendor GPU procurement to reduce vendor lock-in and create negotiating leverage with NVIDIA. You don’t need to deploy to Chinese clusters—plenty of European alternatives exist, from OVHcloud to Nebius. The point is having a credible backup plan and using it.
Third: when you’re evaluating new inference or training systems, default to architectural patterns that don’t assume CUDA. Open standards and abstraction layers add a small performance tax, but they’re insurance against lock-in and supply chain surprises. US export controls tightened again in January 2026, and while European buyers aren’t subject to the same restrictions as Chinese firms, supply chains can still seize up. Optionality is risk management.
Frequently asked questions
What does “GPU density” actually mean?
It’s how many GPUs fit into one physical cabinet or rack. Higher density means less cabling, lower power consumption per unit, faster interconnects between chips, and simpler hardware management. The Tiangai at 144 GPUs is pushing against thermal and power limits—further gains require architectural innovation, not just stacking more chips.
Should we be using Chinese GPU clusters?
For most European SMBs? Probably not yet. The cost advantage is real, but the friction is high: integration complexity, talent familiarity, regulatory uncertainty, and geopolitical risk. But start monitoring the space. Run benchmarks. In 18 months, the trade-off equation will look different.
How do I know if I’m locked into NVIDIA?
Your infrastructure is CUDA-locked if your GPU code depends on NVIDIA-specific libraries and can’t be recompiled for another vendor without major rewrite. If your inference pipeline runs on vLLM or ONNX Runtime with pluggable GPU backends, you have optionality. Audit your stack honestly.
The bigger picture
This is part of a structural bifurcation in AI infrastructure. The US, Europe, and China are building separate but increasingly mature ecosystems. The split is real and permanent. The advantage for European SMBs is that bifurcation breaks monopolies and forces vendor discipline.
Take the strategic win: negotiate harder with NVIDIA because you have credible alternatives. Build with open standards because it keeps you flexible. Monitor Chinese infrastructure because understanding your competition is always smart. The Tiangai 300 is not revolutionary. It’s a signal that revolution was already underway.
Sources
- NVIDIA’s AI chip market share in China drops to 34% in H1 2026
- GPU Infrastructure TCO Model
- CUDA Lock-in Unpacked — The Software Moat, the Real Switching Costs, and How They Are Changing
- Shanghai Iluvatar CoreX Unveils Multi-Year GPU Architecture Roadmap—Tom’s Hardware
- China AI Chips: WAIC 2026 Super-Node Showdown Challenges Nvidia—China Biz Insider
- European GPU Cloud Comparison 2026: Sovereign AI Infrastructure—Lyceum Technology




0 Comments